What is the market overview of the Loitering Munitions Market?
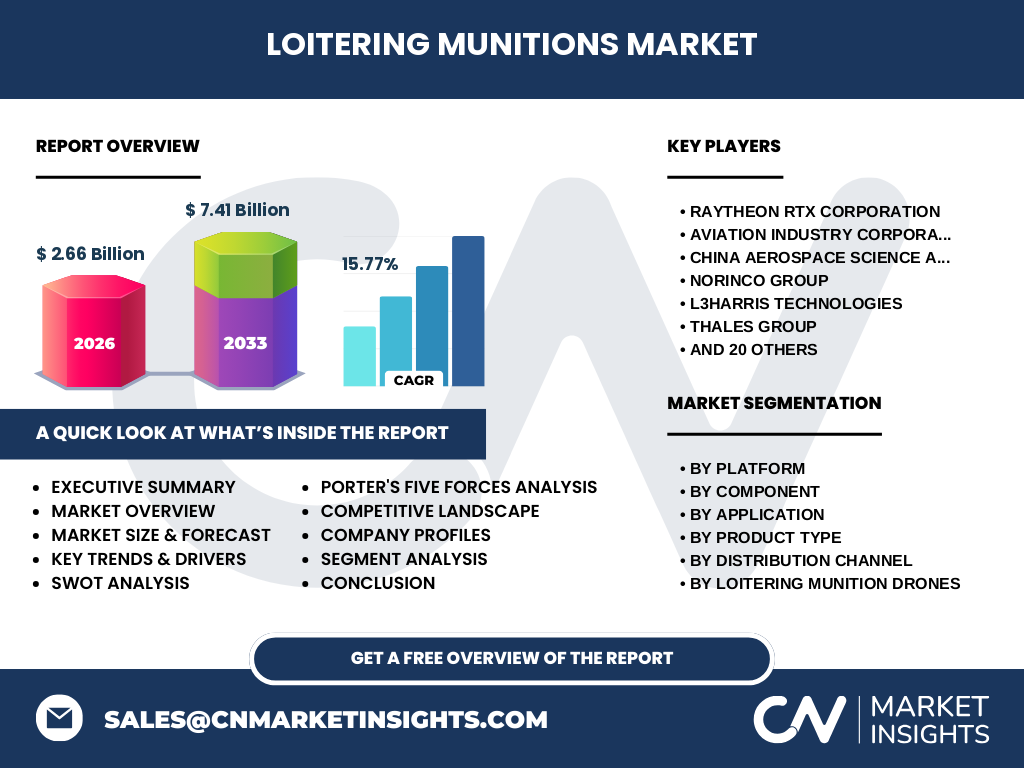
Our analysis indicates the Loitering Munitions Market market size is valued at 2.66 Billion in 2026. This sector bridges traditional artillery and tactical drones, providing defense forces with persistent surveillance and precision strike capabilities governed by strict ITAR regulations and export controls.
Key market drivers, restraints, challenges, and opportunities shaping Loitering Munitions Market
Growth is propelled by rising asymmetric warfare and demand for low-collateral precision strikes. Conversely, supply chain bottlenecks for critical rare earth elements and encrypted Data Link Communication Modules constrain production, creating lucrative opportunities for autonomous swarming technologies developed by innovators like Anduril Industries.
Emerging trends and growth patterns in Loitering Munitions Market
The industry is witnessing a rapid shift toward artificial intelligence-enabled autonomous terminal guidance. Loitering Munition Drones equipped with advanced computer vision are reducing reliance on GPS in contested electronic warfare environments, heavily favoring agile technology developers over legacy primes.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe tier-2 component disruptions for essential Battery Packs and semiconductor chips. However, the subsequent post-pandemic geopolitical escalation accelerated defense budget authorizations worldwide, driving a swift and aggressive recovery across the entire tactical munitions supply chain.
Competitive landscape of the Loitering Munitions Market
The market features a dual-tier structure dominated by defense primes like Israel Aerospace Industries IAI and AeroVironment Inc., alongside agile startups. Market concentration is intensifying as major players acquire niche autonomy providers to secure proprietary Launcher Units and guidance intellectual property.
Executive summary of key findings for the Loitering Munitions Market
Driven by modern doctrinal shifts toward cost-effective precision ordnance, our research forecasts the market to surge from 2.66 Billion in 2026 to 7.41 Billion by 2033 at a robust CAGR of 15.77%, fundamentally transforming modern battlefield logistics.
Market forecast from 2027 to 2033
The market is projected to expand from 2.66 Billion in 2026 to reach 7.41 Billion by 2033, expanding at a remarkable CAGR of 15.77%. This trajectory reflects sustained long-term procurement commitments by NATO and allied Ministries of Defense for attritable precision systems.
Segmentation analysis by platform, component, application, and product type
The market bifurcates across multiple vectors. Platform segments cover Land Based, Naval Based, and Airborne Platforms. Component categories include Warhead Payload Modules, Ground Control Stations, and Data Link Communication Modules. Applications span Surveillance And Reconnaissance, Target Acquisition, and Precision Strike.
Regional market analysis and geographic distribution
Geographic performance highlights strong adoption in Eastern Europe, the Middle East, and the Asia-Pacific. Regional variances are dictated by localized threat environments, defense modernization budgets, and stringent domestic regulatory approvals overseen by bodies like the US Department of State.
In-depth regional review of key markets
North America leads in R&D expenditure through prime contractors like Raytheon RTX Corporation and L3Harris Technologies. Meanwhile, the Asia-Pacific region demonstrates the fastest volume procurement, led by domestic defense initiatives from entities such as Hindustan Aeronautics Ltd HAL and AVIC.
Company profiles and strategic positioning of leading players
Industry leaders leverage distinct competitive moats. AeroVironment Inc. and AeroVironment Inc. dominate man-portable tactical systems, while Elbit Systems Ltd. and UVision Air Ltd. specialize in advanced canister-launched precision munitions integrated seamlessly into armored brigade combat teams.
Porter's Five Forces analysis of the industry
Supplier power remains moderate due to specialized military-grade composite materials and secure Data Link Communication Modules. Buyer power is heavily consolidated among national governments, while the threat of substitution is low given the unique tactical convergence of surveillance and kinetic strike.
SWOT analysis of the Loitering Munitions Market
Core strengths lie in low operational costs relative to cruise missiles. Weaknesses involve electromagnetic vulnerability. Opportunities abound in AI-driven autonomous swarming, while significant threats stem from international arms control treaties and counter-uas directed-energy weapon proliferation.
Value chain analysis from raw materials to end-users
The value flow initiates with raw aerospace-grade carbon fiber and energetic materials suppliers, advancing through specialized sub-assembly integrators producing Warhead Payload Modules and Battery Packs, culminating in direct military procurement via defense contractors.
Investment insights and high-potential areas
Investors should target early-stage innovators specializing in Reusable Loitering Munition Platforms and AI-enabled edge computing. Companies mastering return-and-relaunch mechanics and resilient mesh-networking command the highest valuation upside in the current defense technology cycle.
Conclusion and key takeaways for stakeholders
The Loitering Munitions Market represents a foundational pillar of modern defense modernization. Achieving a projected 7.41 Billion by 2033, success hinges on securing resilient supply chains for Launcher Units and integrating advanced autonomous software.
Research methodology for baseline estimates and data triangulation
Our analysis is synthesized through rigorous data triangulation, combining trade registry filings, procurement budget allocations from defense ministries, secondary macroeconomic indicators, and primary interviews with chief technology officers across top-tier defense contractors.
Scope of the report, coverage parameters, and limitations
This report covers global deployment metrics across land, naval, and airborne domains from 2026 to 2033. Limitations include restricted access to classified black-budget R&D expenditures and unverified clandestine state-actor procurement programs operating outside standard export frameworks.
Recent developments in company announcements, product launches, and partnerships
Recent milestones feature strategic joint ventures between Western defense integrators and agile tech firms to co-develop tube-launched canister systems. Companies like Anduril Industries and Roketsan A.Ş. have aggressively expanded production footprints to fulfill multi-million-dollar defense export orders.